A market concentrated in few hands
Spain's high-end residential market has, over the past few years, matured into something genuinely distinctive. The numbers are striking in their concentration. According to data compiled by the property platform Idealista, there were 46,454 homes listed across Spain for more than one million euros. Yet the further up the price ladder you climb, the narrower the geography becomes.
At the very top, 10,511 properties were listed above three million euros. Three regions alone accounted for around 80 per cent of them. Málaga led with 3,671, the Balearic Islands followed with 2,942, and Madrid contributed 1,830. Barcelona and Alicante trailed some distance behind. The picture is clear enough. Spanish ultra-luxury is not spread evenly across the country but anchored in a handful of coastal and capital strongholds.
The Balearic paradox
The Balearics offer the most interesting case study. The archipelago holds 28 per cent of the entire Spanish supply of homes priced above three million euros, second only to Málaga. For an international buyer, the appeal is self-evident. Limited land, reliable climate, strong connectivity and a degree of security that is increasingly valued. A property valued at several million euros here is no longer simply a residence. It functions as a wealth asset, a base and a statement of intent.
Yet this strength sits alongside a genuine structural tension. The same scarcity of residential land that drives the premium market also constrains supply for the local population. The islands attract international capital while struggling to house the workers who sustain their economy. The ultra-luxury segment is, in this sense, a symptom of a wider polarisation rather than its sole cause.
Madrid's year-round gravity
If the Balearics are the seasonal magnet, Madrid is the year-round engine. Ministry of Housing figures show that the Community of Madrid recorded more than 1,300 sales of large homes above one million euros, the highest of any region. The market here draws on a blend of wealthy domestic households, corporate buyers and an expanding international clientele.
Demand tends to settle in the familiar quarters. Large apartments in Salamanca and Chamberí, family homes in Pozuelo de Alarcón and La Moraleja. What distinguishes Madrid is depth. It is not reliant on a single season or a single nationality, which makes its upper tier unusually resilient.
The Costa del Sol holds its crown
Andalusia remains the undisputed leader of southern luxury. More than 640 large homes above one million euros changed hands across the region, and over 500 of those were in Málaga province alone. Marbella continues to anchor the market, supported by Mijas, Estepona and the low-density enclaves of Benahavís. Further west, Sotogrande in Cádiz adds a quieter, more discreet flavour.
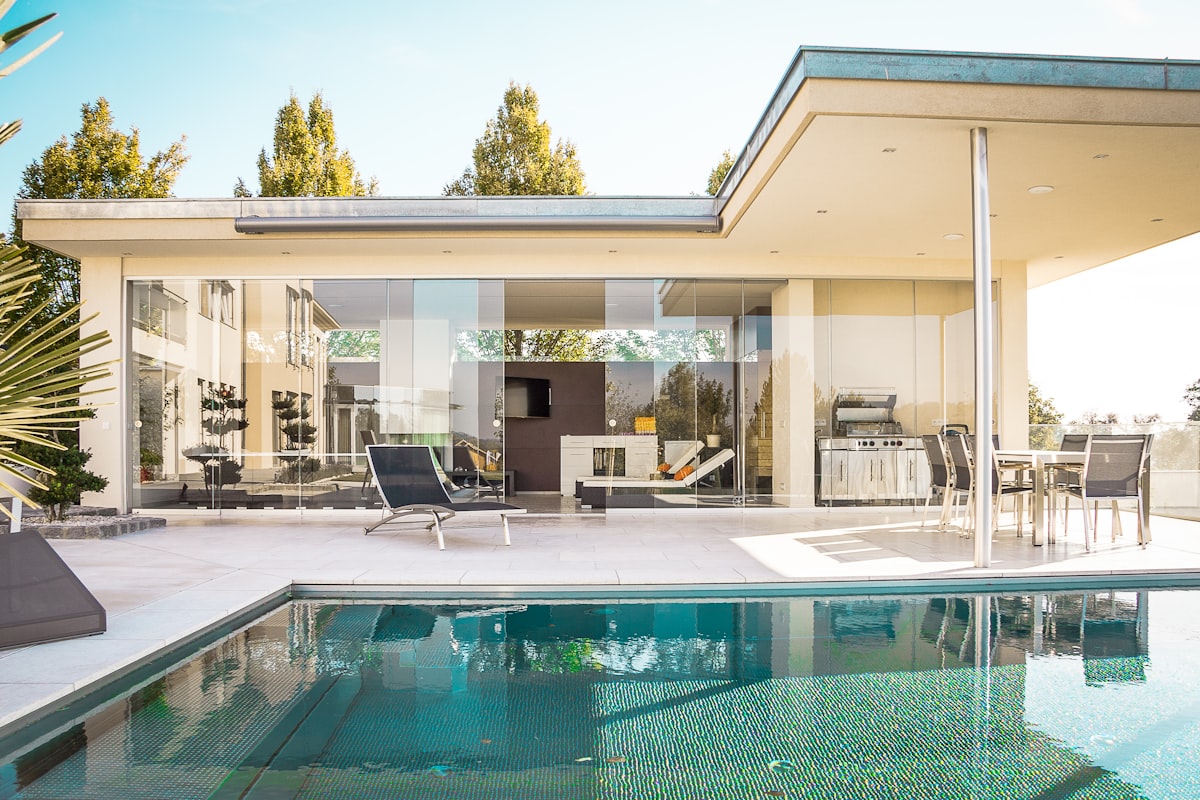
The typical product has changed little. Detached villas with sea views, gated communities around golf courses, and generous penthouses on the seafront. What has changed is the volume of buyers from the Middle East, northern Europe and the Americas willing to commit serious capital to the coastline.
Barcelona and the premium of scarcity
Barcelona presents a different proposition. According to the advisory firm Savills, prime property values rose by 8.6 per cent during 2024 and have continued to climb. The rarest homes now fetch up to 18,000 euros per square metre, with the average luxury property commanding around 9,300 euros. The reason is simple. Genuine scarcity.
A penthouse with uninterrupted views of the Sagrada Família, or a high-ceilinged apartment in the Gothic Quarter with its original mouldings intact, cannot simply be replicated. Buyers who recognise this act quickly, knowing that a comparable opportunity may not return for years. The market has spread beyond Passeig de Gràcia into Eixample, Sarrià-Sant Gervasi and the modern waterfront of Diagonal Mar. Engel and Völkers report that half of Barcelona's transactions above one million euros took place in Sarrià-Sant Gervasi, with 12 per cent of homes sold there exceeding two million.
A potential shift lies ahead. Barcelona plans to phase out its licensed tourist apartments by November 2028, which could release a wave of stock back onto the market. Whether that supply proves unique enough to tempt discerning buyers is another question, but it may at least ease the pressure.
The off-market economy
Beneath the published listings, a parallel market has quietly professionalised. Industry estimates suggest that between 20 and 30 per cent of high-value transactions in 2025 closed without ever appearing on a property platform. These are the off-market sales, directed exclusively at pre-qualified buyers with the proven means to complete.
The motivation is privacy. The sellers are executives, athletes, public figures and international principals who have no interest in exposing the location, contents or even the existence of their homes. Prices in this segment typically begin around 1.75 million euros and can reach 14 or 16 million. For the most exceptional assets, private sale has become the norm rather than the exception.
There is a cost to this discretion. A reduced pool of buyers means fewer competitive offers. Yet for many owners, peace of mind carries a value that no marginal price improvement can match.
Institutional capital takes notice
The interest is not confined to private buyers. Speaking at the Madrid Real Estate Exhibition, the head of BlackRock in Spain described the domestic market as the most attractive in Europe, noting that the country now dominates discussions in international investment committees. A senior figure at Cheyne Capital went further, stating that for the first time Spain had become the continent's number one destination for real estate capital.
The funds are pursuing a broad spread. Student residences, hotels, flexible living and healthcare assets all feature, and affordable housing remains a stated ambition. What is striking is the absence of distress. Executives describe value-added and core strategies rather than opportunistic plays, which suggests a market built on fundamentals rather than speculation.
What it means for buyers
The message for anyone considering an upper-tier purchase in Spain is one of clarity rather than urgency. The strongest markets are well established and unlikely to lose their appeal. Concentration, scarcity and a growing international buyer pool underpin values in Madrid, the Costa del Sol, the Balearics and Barcelona in distinct but durable ways.
The right approach is to treat the purchase as both a lifestyle and a financial decision. Understand the local market's depth, weigh the trade-off between publicity and privacy, and recognise that the most desirable assets are rarely advertised at all. Spain's luxury market has come of age. The opportunity is real, but it rewards the buyer who approaches it with patience and proper counsel.